
Quick Summary
Successfully settling a flood damage insurance claim requires immediate water mitigation and precise documentation within the first 48 hours to clearly establish the moisture origin and satisfy strict carrier deadlines. Partnering with Wade's Restoration streamlines this process by pairing rapid 24/7 emergency water extraction with carrier-ready photo documentation, daily structural drying logs, and itemized scopes that validate your total loss for adjusters. Property owners will understand how to properly document hidden cavity saturation, navigate NFIP filing requirements, and partner with restoration specialists to secure their full settlement fast.
Flood Damage Insurance Claim: Maximize Payout Fast
When water pours into your property, getting your flood damage insurance claim processed depends on what you record in the first 24 to 48 hours. The National Flood Insurance Program (NFIP) handles claims across the country, backed by a public claims dataset covering flood loss transactions. Proper documentation of the water source and structural damage is essential to support a claim.[1]
Wade’s Restoration provides 24/7 emergency response across Astoria, Queens, and Lower Manhattan, dispatching IICRC-certified technicians. Through structured moisture documentation and drying logs, our team helps homeowners and property managers record damage before insurance adjusters arrive on site. See also Flooded Basement Cleanup – Call Now-10% Off – Same-Day Service – Free Estimate.
Flood Damage Insurance Claim: What You Need to Know First
Quick Overview: Filing a flood claim requires clear photo documentation, fast water extraction to prevent secondary damage, and notifying your insurer within policy time limits (the NFIP proof of loss is due within 60 days unless FEMA grants an extension). Standard homeowners or renters policies do not cover overland flooding, which requires a separate flood policy. However, standard policies often cover sudden internal plumbing breaks. Proving where the moisture originated is a critical step in securing coverage.[3]
Handling a water loss starts with identifying the exact water source. Standard property insurance covers sudden interior plumbing failures, such as a frozen radiator line or a burst supply pipe. Flood insurance, typically written through the NFIP or private specialty carriers, covers overland flooding and surface water runoff. In older buildings, internal pipe breaks can sometimes be confused with ground seepage, making physical proof essential.[4]
What You’ll Need Before You Begin
To prepare your claim records before the adjuster arrives, gather the following:
- Policy Declaration Pages: Your active NFIP policy details, private flood endorsements, or standard property coverage forms.
- Time-Stamped Visual Records: Clear photos and videos showing water height lines, floor saturation, and structural entry points before cleanup begins.
- Moisture Records: Documentation tracking moisture levels in affected building materials.
Key Filing Takeaways at a Glance
FEMA maintains a public NFIP claims dataset and tracks multiple-loss properties, including repetitive loss and severe repetitive loss properties. An independent analysis by Resources for the Future found that across 35 years of NFIP records, the mean flood claim was $33,764 (in 2012 dollars) and the median was $12,555. Securing a fair settlement requires documenting damage with objective data rather than relying solely on a visual walk-through.[2]
Step 1: Document Water Source and Structural Entry Points
Pinpointing the exact point of entry establishes whether your loss falls under standard property coverage or a flood policy.
Distinguishing Plumbing Failures from Rising Ground Water
Tracking the water’s path before it drains is critical. If water originates from an internal pipe break on an upper floor or behind a wall, your standard property policy should respond. If water enters from street-level runoff or surface flooding, it falls under flood coverage. Documenting the highest point of moisture helps determine the origin of the water.
The Pre-War Brick Party Wall Complication
In attached row houses and older walk-ups, shared masonry party walls can complicate moisture tracking. Brick is porous and can pull water both horizontally and vertically through capillary action. When a neighbor’s pipe bursts or an internal pipe fails inside a wall cavity, moisture spreads throughout the brickwork.
To document moisture migration accurately:
- Moisture Mapping: Thermal imaging and moisture meters can help track moisture migration patterns along building assemblies to help identify the source.
- Moisture Readings: Probe meters document moisture levels near internal supply lines versus foundation bases to show where moisture is concentrated.
Step 2: Mitigate Immediate Loss to Prevent Claim Denials
Need flood damage insurance claim?
We’re available now - call for a fast, free estimate.
Property insurance policies typically contain a duty to mitigate damages, requiring reasonable steps to prevent further damage after a loss occurs.
Protecting Subfloors, Joists, and Basements
Take direct containment steps as soon as it is safe to enter:
- Extract standing water using commercial extraction units.
- Inspect structural framing along walls and remove baseboards to allow air circulation behind plaster or drywall surfaces.
- Deploy dehumidifiers and air movers to remove moisture from structural materials.
Preventing Secondary Mold
According to Wade’s Restoration, prompt water extraction and active drying help prevent secondary mold growth and protect structural materials from unnecessary deterioration.
Step 3: Build an Itemized Inventory and Moisture Record
Building an itemized inventory supported by moisture logs turns broad damage estimates into concrete line items during the claims process.
Room-by-Room Content Categorization
Walk through each room systematically to record personal property and structural components:
- Record descriptions, model numbers, estimated age, and replacement costs for damaged items.
- Take clear photos of serial numbers on boilers, water heaters, major appliances, and electrical panels before removing them.
- Keep samples of high-value flooring, wall coverings, or custom trim before disposal so materials can be verified.
Drying Records
Keep daily drying records that document:
- Ambient temperature and relative humidity readings in affected rooms.
- Moisture levels in affected framing, subfloors, and wall materials.
Step 4: File the Formal Notice of Loss with Your Carrier
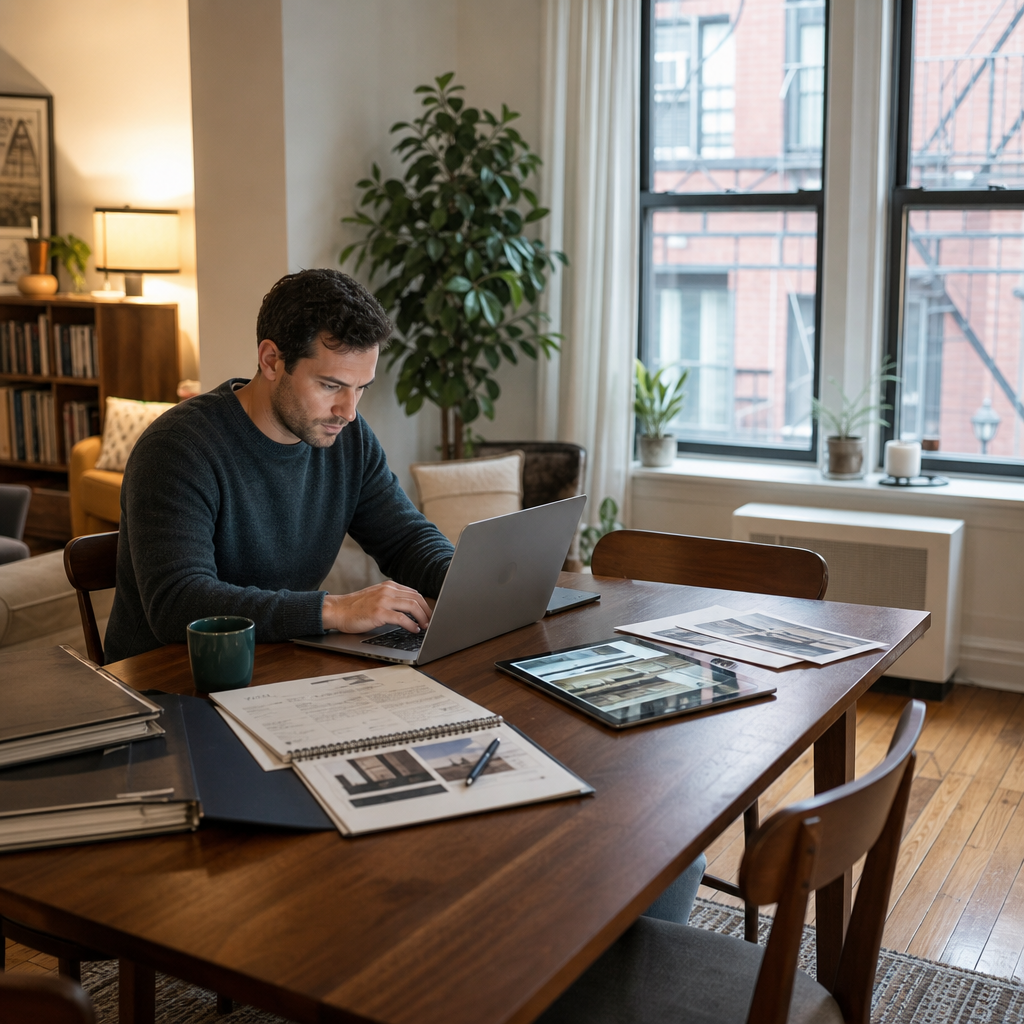
Timelines govern every insurance claim. While standard private policies require prompt notice, National Flood Insurance Program policies have specific filing requirements.
Standard Property vs. NFIP Policy Deadlines
| Policy Type | Initial Notice Window | Proof of Loss Requirement |
|---|---|---|
| Standard Homeowners / Commercial | Prompt notice | Submitted upon insurer request |
| NFIP Flood Policy | Prompt notice of loss | Due within 60 days of loss unless FEMA grants an extension |
Filing the NFIP Proof of Loss Statement
Under NFIP guidelines, the proof of loss form is due within 60 days of the loss unless FEMA grants an extension. This document outlines your claim, including itemized repair estimates and inventory lists.
Step 5: Navigate the Insurance Adjuster On-Site Inspection
Need flood damage insurance claim?
We’re available now - call for a fast, free estimate.
The field adjuster inspects the property to estimate repair costs. Walking the property alongside the adjuster with your moisture records, as advised by Wade’s Restoration, helps ensure all damaged areas are evaluated.
Walking the Property with Documentation
Surface materials can appear dry while trapping moisture inside cavities. During the inspection:
- Demonstrate cavity saturation: Use moisture meters to show moisture levels behind baseboards, sill plates, and framing assemblies.
- Review affected materials: Point out saturated insulation and wall materials that require drying or removal.
Addressing Scope Discrepancies
If an adjuster’s initial scope omits necessary line items like subfloor drying, structural treatments, or electrical repairs, request a scope review. Submit your drying logs, photos, and itemized restoration documentation as supporting evidence.
Step 6: Finalize the Scope and Complete Reconstruction
Closing your claim requires reconciling the adjuster’s estimate with actual rebuilding costs. Once structural drying is complete, you will transition into the reconstruction phase to rebuild walls, floors, and finishes.
Reconciling the Scope of Work with Payouts
Review the adjuster’s line-item summary against current local labor rates and material costs. If the settlement check comes with an initial depreciation holdback (Recoverable Depreciation), submitting final completion invoices and documentation will help release the remaining funds.
Moving from Drying to Rebuild
Working with a contractor capable of managing both mitigation and structural rebuild keeps documentation consistent:
- Secure agreement on the scope before finishing drywall, flooring, and trim.
- Ensure moisture readings indicate the structure is adequately dry before closing up wall cavities.
- Submit final completion documentation to your carrier for final claim closure.
What Does Flood Damage Restoration Cost?
Emergency water mitigation costs vary based on water category (clean, grey, or black/sewage), building materials, and saturation depth. Professional mitigation for residential and light commercial properties typically ranges from $1,500 to $10,000 or more. Reconstruction costs are calculated separately based on square footage and finish materials.
Typical Industry Price Ranges
| Restoration Phase | Average Industry Range |
|---|---|
| Moisture Inspection & Assessment | $0 – $450 |
| Structural Water Extraction & Drying | $1,500 – $4,800 |
| Floodwater Sanitation | $2,200 – $7,500 |
| Mold Remediation & Treatment | $1,800 – $6,500+ |
| Structural Reconstruction & Repairs | $5,000 – $25,000+ |
Protecting Your Settlement
Having thorough documentation and itemized estimates protects property owners by ensuring scopes reflect actual job site conditions. Wade’s Restoration provides moisture tracking and itemized documentation to assist property owners during the claims process.
Frequently Asked Questions About Flood Damage Insurance Claims
Does standard homeowners insurance cover flood damage?
No. Standard homeowners and commercial property policies explicitly exclude damage caused by rising surface water, storm surges, or overland flooding. Those events require a dedicated flood insurance policy through the NFIP or a private carrier. Standard policies do, however, cover sudden and accidental internal plumbing breaks, such as burst supply pipes.[5]
How long does an insurance company have to pay a flood claim?
An NFIP loss is payable 60 days after FEMA receives the proof of loss, or after the adjuster report in lieu of proof of loss, once agreement, judgment, or appraisal occurs.
Can a restoration contractor help negotiate with my insurance adjuster?
Restoration contractors cannot negotiate financial settlements unless they are licensed public adjusters. However, restoration professionals like Wade’s Restoration routinely provide technical documentation, drying records, and itemized estimates that document the conditions on the property.
What should I do immediately after my house floods before the adjuster arrives?
First, ensure personal safety by shutting off electricity to affected areas if water levels reach outlets. Take clear photos of standing water, waterlines on walls, and damaged items before moving anything. Then, begin emergency water extraction and drying to mitigate further structural damage.
Need flood damage insurance claim?
We’re available now - call for a fast, free estimate.
Sources
- FEMA Exercises Borrowing Authority for National Flood Insurance Program – fema.gov (2025)
- [PDF] national flood insurance program – media toolkit – agents.floodsmart.gov (2024)
- Introduction to the National Flood Insurance Program (NFIP) – congress.gov (2024)
- Historical NFIP Claims Information and Trends | The National … – floodsmart.gov
- The NFIP: GAO Report to Congress – soa.org (2023)
Related reading: Best Way to Remove Water From Basement – 10% Off & Free Estimate – Same-Day Service
Related reading: Black Mold Removal – Call Now-10% Off – Same-Day Service – Free Estimate
Related reading: Burst Pipe Water Damage – 10% Off & Free Estimate – On-Site in 60 Minutes
Frequently Asked Questions
Can I begin removing flooded drywall and flooring before the insurance adjuster arrives?
Yes, property owners have a duty to mitigate damage immediately to stop secondary mold growth, provided thorough evidence is captured first. Wade's Restoration takes detailed timestamped photos, saves material cutouts, and maintains moisture logs so you can safely begin water extraction without risking claim denial.
What should I do if the adjuster's initial flood claim estimate is too low?
You can request a scope revision and file a supplemental claim by submitting objective moisture data and contractor estimates. Wade's Restoration supports policyholders with line-item scopes, daily structural drying records, and cavity saturation proof that directly demonstrate missed repair costs to your carrier.
How do I get my insurance company to release recoverable depreciation funds?
To collect withheld depreciation, you must submit final paid invoices and completion documentation showing repairs were completed within policy guidelines. Wade's Restoration manages both water mitigation and structural rebuilds, providing the finalized line-item billing packets required to expedite the release of your holdback check.
About the author
 |
Sarah Miller Sarah Miller is a certified water damage restoration specialist with over eight years of experience helping property owners navigate the complexities of mitigation and recovery. She holds an associate degree in Construction Management from New York City College of Technology and has extensive knowledge of local building codes and insurance claim procedures. Through her writing, Sarah provides actionable advice to help property managers and homeowners in the Astoria area understand the true costs and critical steps involved in emergency water damage restoration. |
Water damage, flood, or mold emergency?
We’re available now - call for a fast, free estimate.
Call Now - Free Estimate